Abstract
Albert has over 10M installs and a 4.5★ lifetime rating, but recent long reviews repeatedly complain about forced subscriptions, hard cancellation, money moved into savings, repayment/linking issues, and bot-like support. The gap is real, but a solo builder should not try to clone banking, loans, investing, or advances; the viable wedge is a no-custody budgeting and subscription-tracking app that wins on transparency.
Background
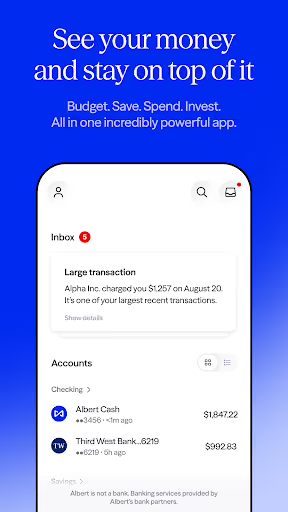
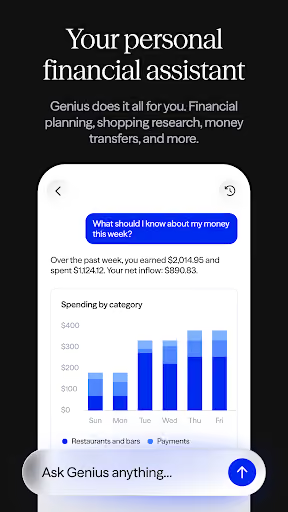
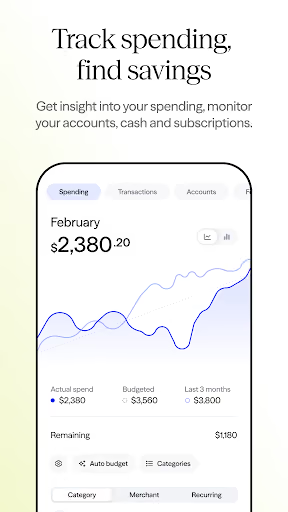
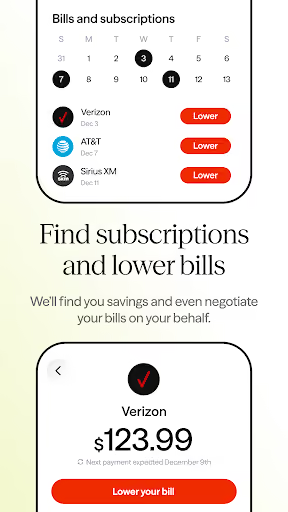
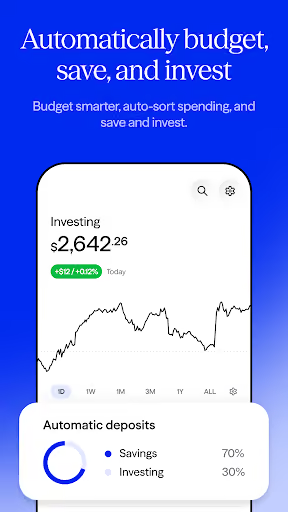
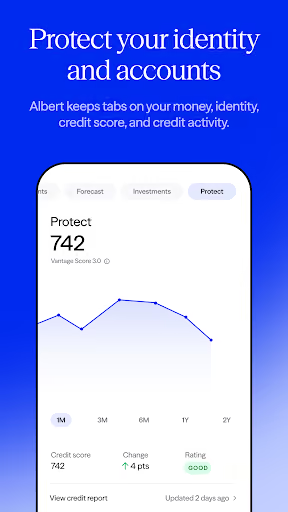
Albert: Budgeting and Banking is positioned as an all-in-one money app: budgeting, banking, savings, investing, identity monitoring, cash advances, loans, and an AI financial assistant. The Play listing says the app is free, but also says a subscription is required and Albert plans range from $19.99-$39.99.
What it does
Aggregates accounts, budgets, recurring bills, savings, investing, direct deposit, cash advances, loans, identity monitoring, and AI help in one finance app.
What changed
Reviewers describe rising or unexpected monthly charges, subscriptions they say they did not knowingly choose, and cancellation blocked by balances, pending transactions, or verification flows.
Why it is soft
The anger is not just about price; it is about trust. A simpler app that never holds user funds can avoid the exact trap users are describing.
Strengths
This is not a weak incumbent. Albert has a large install base, a high lifetime rating, and a broad feature bundle that a solo builder cannot replicate. Some reviewers still say the cash advances are generous or were helpful, and several describe the app as once useful before fees, policy changes, or support problems changed the experience.
Distribution
The listed installs reached 10,109,488 on 2026-09-19, so Albert has search visibility and brand familiarity a new app starts without.
Feature breadth
Banking partners, lending, brokerage, identity monitoring, credit score tracking, and cash advances are all beyond a normal part-time solo build.
User habit
The strongest positive signal is need: users came for budgeting, short-term cash help, savings, or account visibility, not for a novelty app.
Market gap
The most common complaint cluster is cancellation and billing trust, followed by money being moved or held in ways users say block exit, then bank-linking and repayment failures, then support that feels automated or powerless.
Cancellation and billing
Many reviewers say they were charged after canceling, charged without understanding they subscribed, or pushed into $19.99-$39.99 plans they did not value.
Custody trap
A repeated theme is being unable to cancel until savings, investing, advance, or pending balances are cleared, while those balances take days or weeks to move.
Bank and repayment failures
Reviewers describe failed bank verification, repayment that posts at the bank but not in Albert, and locked flows when old bank accounts cannot reconnect.
Support trust
Support is often described as bot-like, email-only, slow, or unable to refund or override obvious edge cases.
THIS APP IS LITERALLY GOING TO ROB YOU They wont let me cancel my subscription because they took(stole) money from my account and put it into some albert savings account, well guess what, you cant cancel your subscription unless the savings account is at 0 and the best part is they wont let me transfer money from my albert "savings" account to my bank account. so basically im trapped! there charging my account 40$ a month for a service im not using! ive tried to cancel multiple times!! PREDATORS
UPDATE: "Emma" isnt even a real person. Just an AI response bot. These people are liars and scammers and probably not even based in the U.S. AVOID LIKE THE PLAGUE! Been trying to pay a loan back that should have been paid in full a while ago, and I literally can't because they need to "verify ownership" of my account! WTH? And service only responds once ever so often, and they act like they don't know what to do! Like I'm literally trying to pay you back, and you're making it impossible!
If you enjoy an unsubscribe process that is more like an escape room than an app, then Albert is for you! Is the app great? I dont know. Does it function as advertised? Maybe? I'll never really know because seperating from Albert is a lot like trying to pull an Alien Xenomorph off your own face. The benefits sort of just get lost in the struggle for control over your wallet. They will tell you its as simple as clicking on a link but you know better. 0 stars if I could.
- Do not hold customer funds in v1. The biggest opening is trust; a read-only or manual budgeting app avoids savings, investing, advances, pending withdrawals, and the exit traps reviewers describe.
- Make cancellation a product feature. Use clear pricing, plain receipts, Google Play billing, an obvious cancel button, and immediate data deletion/export so the app is visibly the opposite of the complaint.
- Replace advances with cash-flow warnings. A solo builder cannot responsibly offer loans without capital and partners, but can warn users before bills, overdraft risk, and subscriptions hit.
Build complexity
Estimated, not derived: one developer, part-time, no funding, no paid acquisition. This is not an Albert clone; it is a narrow no-custody budget tracker with subscription detection, bill forecasts, export, clear billing, and support tooling.
| Workstream | Weeks |
|---|---|
| Trust-first product scope, onboarding, pricing, and cancellation UX | 2 |
| Budgets, recurring bills, subscription list, reminders, and exports | 4 |
| Optional read-only bank-link flow, reconciliation, and fallback manual entry | 4 |
| Security basics, data deletion, audit log, and support inbox | 3 |
| Google Play billing, listing, QA, and launch content | 3 |
| Total | 16 |
Expected revenue
Estimated, not derived: the model is a free manual tracker plus transparent $4.99/mo Pro for bank sync, forecasts, exports, and alerts. The funnel assumes organic Play Store/search traffic only and no forced trial.
| Month 12 funnel | Users | Assumption |
|---|---|---|
| Total installs to date | 5,000 | Organic only |
| Activated budget or subscription tracking | 2,000 | 40% assumption |
| Retained active users | 800 | 16% assumption |
| Paid Pro subscribers | 240 | 4.8% of installs |
| MRR | $1,200 | $4.99/mo rounded |
Biggest challenges
The hard part is not making budget screens; it is earning trust in a finance category after users have been burned, while refusing the features that make Albert valuable to many people: advances, banking, savings yield, loans, investing, and identity monitoring.
No cash-advance clone
Users came for money access, but advances require capital, risk decisions, repayment operations, and banking/lending relationships a part-time builder should not fake.
Financial-data trust
Even read-only bank linking asks for sensitive account access, so onboarding, deletion, security copy, and support have to be unusually clear from day one.
Support burden
The gap is partly human support; if the solo builder cannot answer billing and sync issues quickly, the differentiator disappears.
AI angle
There is a real but limited AI angle: transaction categorization, subscription detection, and plain-English bill explanations can be built faster with modern models than by hand-coded rules alone. But AI is not the differentiator here, and it should not replace human cancellation or billing support because reviewers are already angry at bot-like help.
Useful AI
Classify merchants, detect recurring charges, summarize upcoming cash-flow problems, and draft support replies for the builder to approve.
Do not use AI for
Cancellation, refunds, account deletion, or disputes. Those are exactly where users say Albert’s experience feels evasive.
Conclusion
Skip the full clone. Build only the narrow trust wedge: budgeting, subscription visibility, forecasts, export, and clean cancellation. The complaint is strong enough to support a small indie app, but Albert’s real moat is not code; it is banking, lending, compliance, capital, and distribution.
16 weeks
Time to v1
$4.99/mo
Transparent Pro plan
$1,200
Estimated month-12 MRR
Bank partners
Deciding constraint